How Do You Know Whether It’s Time? A Completely Confidential Conversation on Nonprofit Dissolution
Video:
Accompanying Slides: Download here.
Transcript: Coming Soon.
Resources
Even though nonprofits are often born from a community’s collective will, many forget that this will grows more valuable to an organization’s economy as the group matures and builds trust and reputation. For some organizations, this collective will becomes the driving and decision-making force when the organization runs into financial trouble. You can see how this plays out in the two articles that follow.
Making the Most of Stakeholder Revolt: The Recapturing of the San Diego Opera and Sweet Briar College
The Voice from Outside: Stakeholder Resistance in Nonprofit Organizations
Social capital is a pivotal resource when a nonprofit faces an existential threat—or is even given up for dead by its own inattentive board. It’s rarely discussed, but often utilized when threats permeate. We started the webinar with that concentration, and a little guidance about how to build, gauge, and mobilize the social capital around an organization.
The word “fiduciary” is often used in nonprofit governance and management, too. Our resources are meant to be put to work in an optimal fashion for the best interests of those in whose name we do business. But few imagine how long it takes to go out of business while observing the highest standards of stewardship. For many mature organizations with assets, an honorable dissolution process requires tireless, unstinting, and seemingly endless fiduciary attention. The following article by Traci Lester walks us through what that looks like—and why it is still sometimes the only reasonable choice.
How Dissolving Your Nonprofit Can Strengthen the Sector
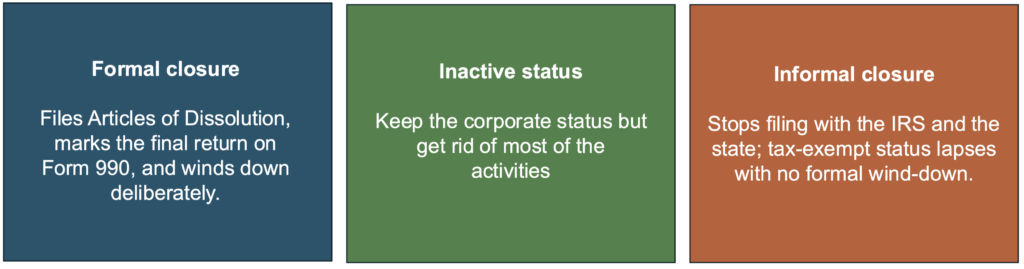
Below are step-by-step guides to the process of closing a nonprofit, which varies legally and administratively state by state. We begin with a grid that pertains to the level of formality and finality you must observe.
Wrapping Up With Paperwork—or Without It
Closure itself isn’t always a managed process.
Strategic Sunsetting
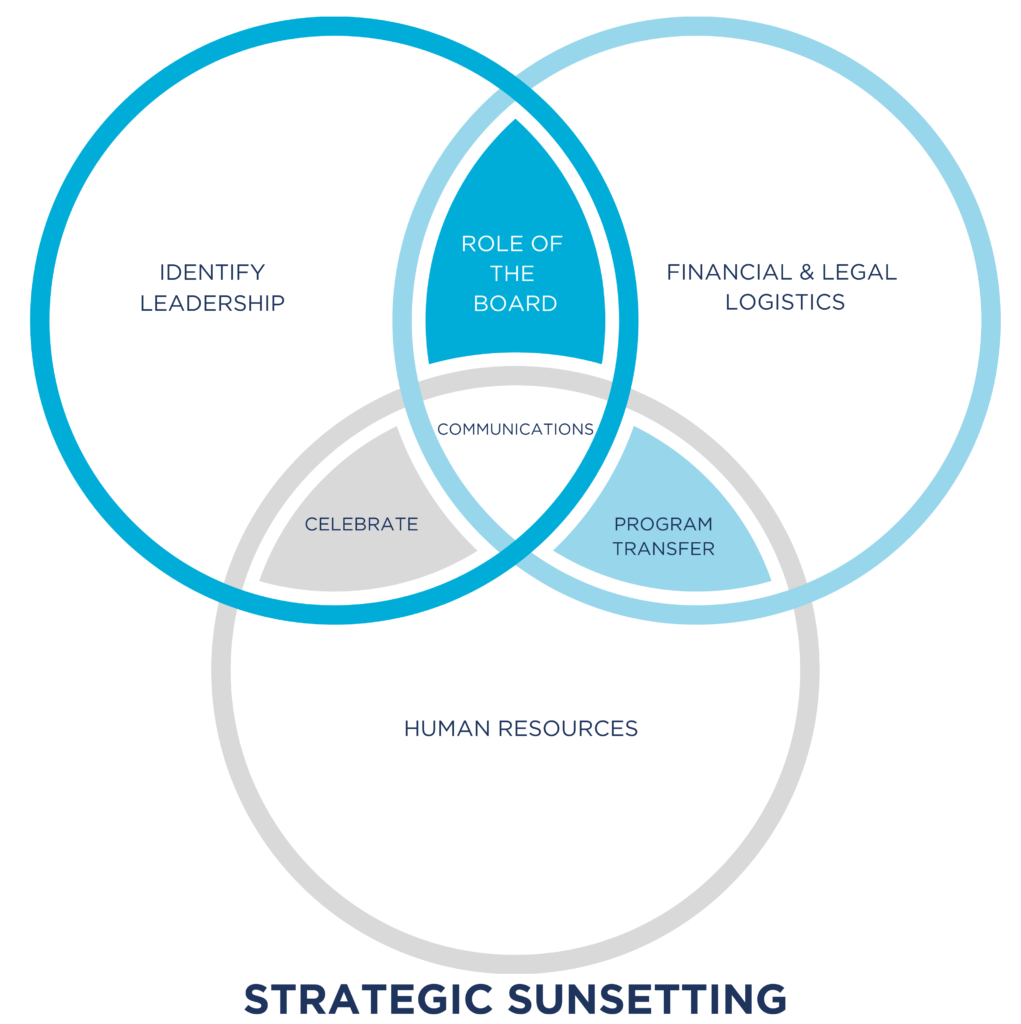
Sunsetting can be a normal, mission-focused part of an organization’s life cycle and occurs when the work an organization set out to do has been done, capacity has been reached, and energy and resources are needed elsewhere.
Sunsetting is a strategic decision that requires transparency, honesty, and planning. The often emotionally charged task of bringing sunsetting into strategic conversations can be difficult for organizational leadership to confront. With that in mind, how can you and your organization prepare to confront the possibility of closure with a clear mind and intentional, empathetic decision making?
Nonprofit Dissolution: What to Do When Closing the Doors
Legal and Regulatory Issues
- Dissolution is a highly regulated process.
- Specific requirements vary by state:
- Role of office of Secretary of State
- Corporate record, end of corporate existence
- Simply filing Articles of Dissolution with the Sec’y of State is often insufficient for a charitable corporation.
- Role of Attorney General/charities regulator
- Charities registration
- Supervision of disposition of charitable assets
- Role of office of Secretary of State
- IRS filings for employment tax and information return termination are specific and a compliance priority.
- Records retention required for up to four years.
Typical Order for Dissolving a Charitable Nonprofit
| Order | Step | Typical filing/document | Filed with / handled by |
| 1 | Review governing documents and finances | Articles, bylaws, dissolution clause, grants, donor restrictions, contracts, debts | Internal |
| 2 | Board approves dissolution | Board resolution and Plan of Dissolution | Corporate records |
| 3 | Notify state Attorney General/charities regulator | Notice of Intent to Dissolve and proposed asset distribution | State Attorney General |
| 4 | File preliminary dissolution notice, if required | Notice/Statement of Intent to Dissolve | Secretary of State |
| 5 | Identify and notify creditors | Direct notice; sometimes published notice | Creditors and claimants |
| 6 | Wind up operations | Final payroll, contracts, leases, grants, receivables, sale of property, etc. | Various |
| 7 | Deal with donor-restricted assets | Transfer agreements; donor approval; sometimes AG/court petition | Recipient charity, AG or court |
| 8 | Pay or provide for creditors | Payments, settlement agreements, reserves | Creditors |
| 9 | Distribute remaining charitable assets | Asset-transfer agreements; board documentation | Other qualified charity/government |
| 10 | Complete state corporation dissolution | Articles/Certificate of Dissolution | Secretary of State |
| 11 | Close charitable registration | Final report, withdrawal/termination filing | Attorney General/charities bureau |
| 12 | File final IRS return | Final Form 990/990-EZ + Schedule N; 990-N or 990-PF as applicable | IRS |
| 13 | Complete employee/tax filings | Final Forms 941/944, 940 if applicable; W-2/W-3; 1099s | IRS/SSA/state agencies |
| 14 | Close remaining state/local accounts | Sales tax, unemployment, licenses, permits, fundraising registrations | State/local agencies |
| 15 | Preserve records | Corporate, tax, payroll, donor and asset-transfer records | Organization/custodian |
Three particularly important legal issues in charitable nonprofit dissolution
1. Creditors come before the unrestricted charitable remainder.
A nonprofit cannot decide to give all its cash and property to another charity and leave its creditors unpaid. State nonprofit corporation statutes generally require debts, liabilities and claims to be paid or adequately provided for during the wind-up.
2. Charitable assets do not become the property of the board, founders, or members.
The federal 501(c)(3) rules require charitable assets to remain permanently dedicated to exempt purposes. Upon dissolution, the residual assets generally must be distributed for a 501(c)(3) exempt purpose or to federal, state or local government for a public purpose
3. Restricted gifts are different from ordinary unrestricted assets.
If complying with the restriction has become impossible or impracticable, modification of the restriction may require donor consent, Attorney General involvement, or a court proceeding under applicable state law.